Restaurant Credit Card Processing: Cut Fees Without Slowing Service
You pull up the month-end statement after a busy stretch and the math does not match the rate you were quoted. Tip adjustments sit on their own lines, a few bar tabs settled for more than the card was first approved for, and the online orders carry fees that look heavier than anything run at the counter. Restaurant credit card processing rarely goes sideways because of one bad rate. It goes sideways because tips, open tabs, tableside payments, and online orders are each handled a little differently, and most pricing models and POS setups are not built to show you where the money goes.
Credit card processing for restaurants is really a stack of small cost decisions. Once you can see those costs, you can compare pricing models honestly, ask better questions of any provider, and decide which program fits the way your room actually runs.
What Makes Restaurant Credit Card Processing Different From Other Retail
A retail shop dips a card, gets an approval, and moves on. A restaurant almost never works that cleanly, and each difference shows up somewhere on your statement.
Tips and tip adjustments
In a full-service room, the card is usually authorized for the check amount and the gratuity is added after the guest signs. That is a second step on every tipped ticket. Your POS handles the workflow, but the pricing model behind it decides what that adjusted ticket costs you. Monument makes the point directly on its restaurant and bar POS page: restaurants typically process a high percentage of credit card transactions with tips, and that affects the effective processing cost. A room with heavy tip volume is simply not priced like a shop that never sees a tip line.
Pre-authorized open tabs
When a guest starts a tab at the bar, the card is authorized and a hold is placed. The final amount gets captured later, often after a few more rounds. If the final number lands well above the original authorization, or the tab sits open long after the guest walks out, the transaction can settle differently than it started. In a packed room, small tab errors pile up quickly, and tab management mistakes during high-volume service are one of the first pain points Monument lists for restaurants and bars.
Card-present versus card-not-present
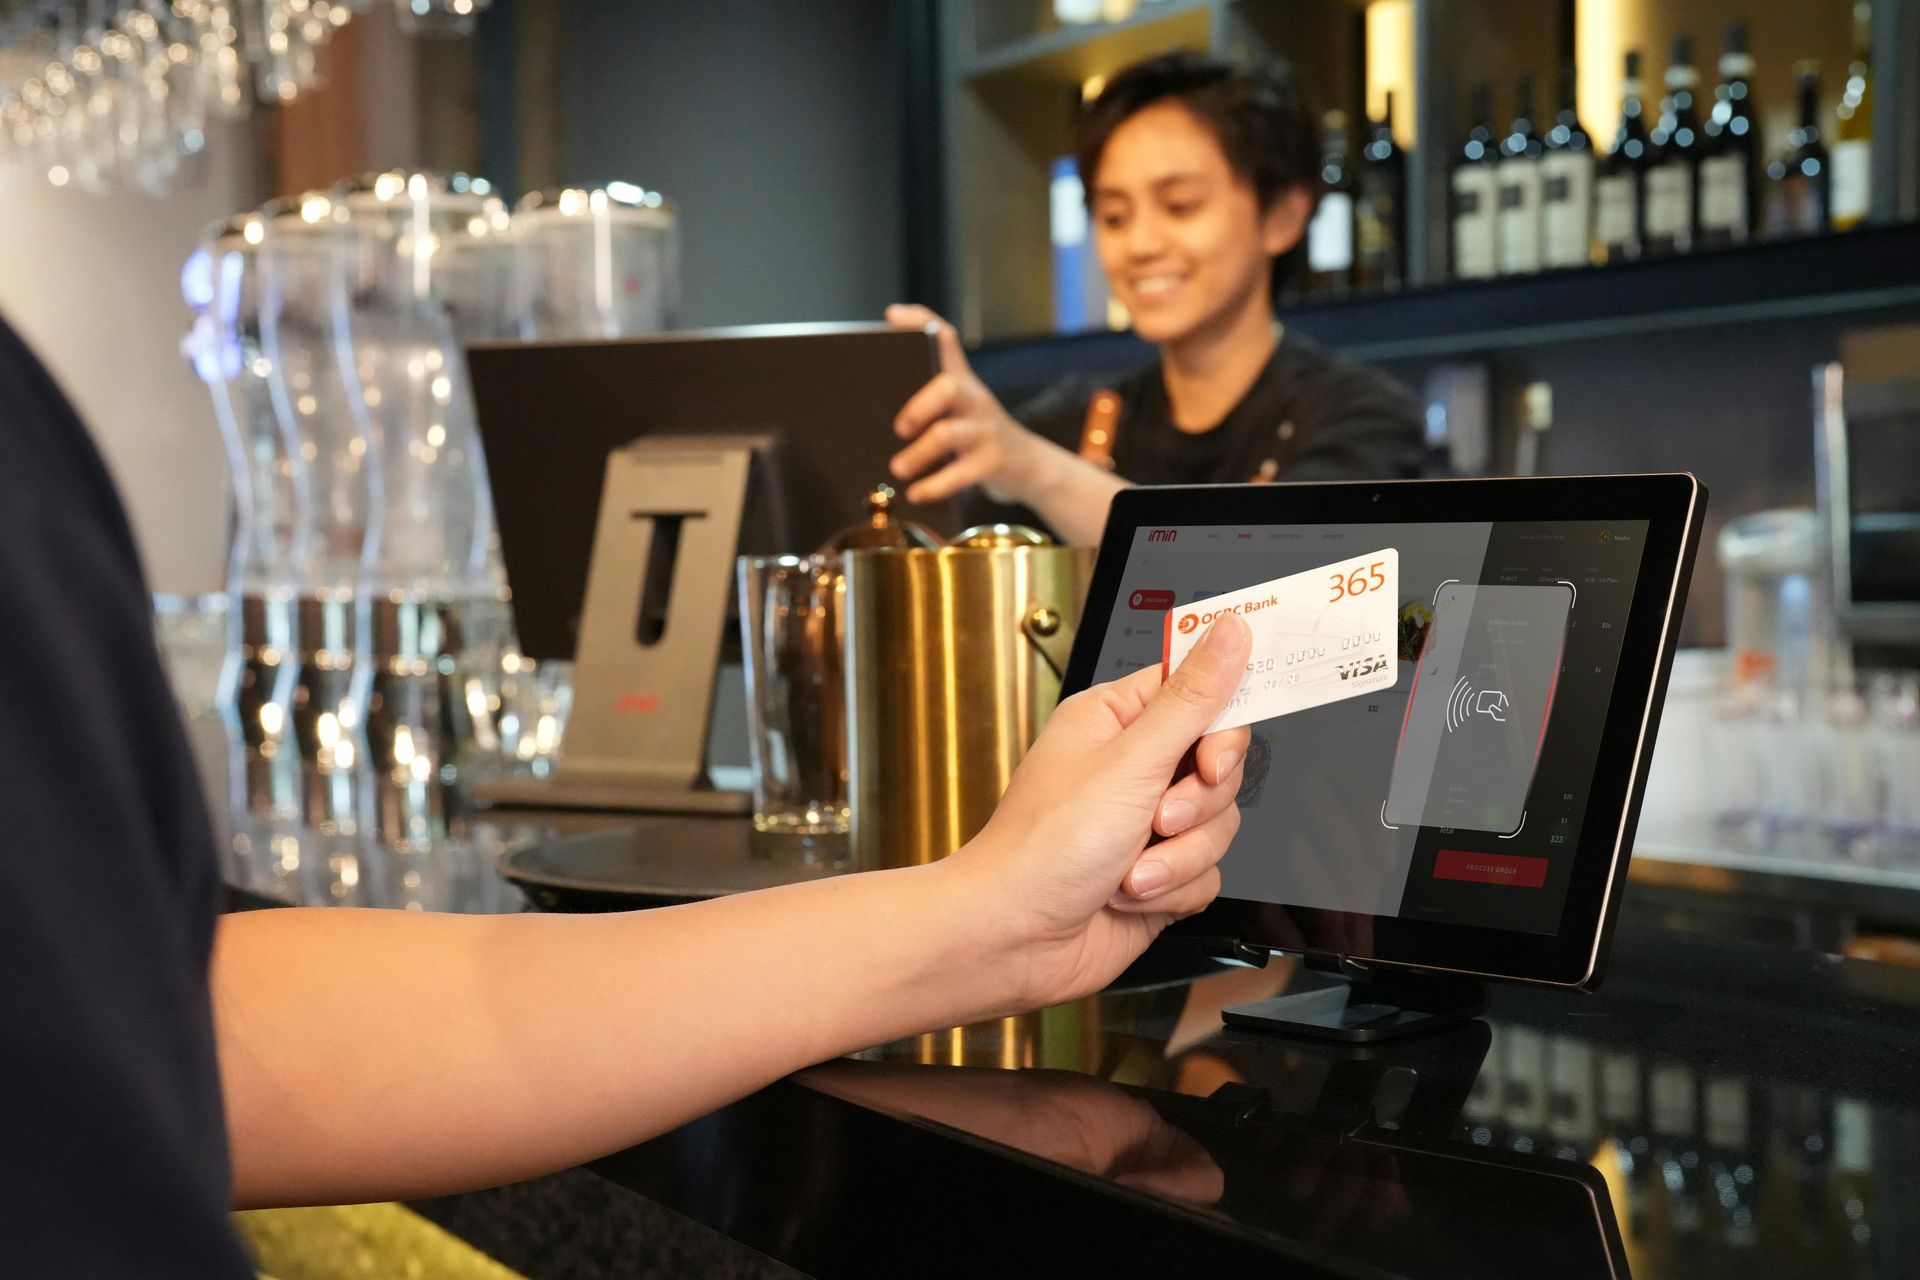
A dip or tap on a countertop terminal or a tableside handheld is a card-present transaction. An order placed on your website or phoned in for pickup is card-not-present. The card networks price these differently because the fraud risk is different, so a restaurant with a real share of online ordering has two cost structures blended into one statement.
Keyed-in transactions
Phone orders, catering deposits, and house accounts often get typed in by hand. Keyed transactions are treated differently than dipped or tapped ones, and they are a common trigger for downgrades, especially under tiered pricing.
Habits that keep costs down without renegotiating anything
Some of the cheapest savings are operational. Run cards present (dip or tap) whenever you can instead of keying them. Close tabs and batch every day rather than letting authorizations sit overnight or longer. Keep tip adjustments inside the same batch as the original sale instead of processing them as separate transactions. None of that requires a new contract. It is closer to closing-shift hygiene.
Delivery apps are a different animal. Orders placed through third-party delivery marketplaces are generally charged by the marketplace itself, so the commission it takes is a separate cost from your own processing, even though both feel like the same leak when you look at margins.
Where Your Fees Actually Go: Interchange, Assessments, and Markup
Every card sale you accept carries three layers of cost. Knowing which layer is which tells you where savings can realistically come from.
- Interchange is set by the card networks and paid to the bank that issued your guest's card. It is usually the largest share of the cost, and your processor does not control it. Visa publishes its U.S. interchange reimbursement fee schedule, and restaurants have their own categories in it, which is a good reminder that how and where a card is accepted changes the underlying cost.
- Assessments are network fees charged on top of interchange. Your processor does not set these either.
- Processor markup is the layer your provider controls, and the only one you can really negotiate.
So when someone quotes you "one low rate," that number is a blend of all three layers. Any savings they promise can only come from a lower markup or from how your transactions are structured and accepted, never from interchange itself. If you want the longer explanation of the most transparent model, we walk through it in interchange plus pricing: what it means and when it fits. The short version: the more clearly those layers show up on your statement, the easier it is to verify what you are paying.
Interchange-Plus vs Flat-Rate vs Tiered Pricing for Restaurants
The three common pricing models behave differently in a restaurant than they do in a simple retail shop, mostly because restaurant statements are messy by default.
Interchange-plus passes the actual network interchange through and adds a fixed, disclosed markup. It is the most transparent model and the easiest to check line by line. That matters when tips, adjusted tabs, and online orders all land in the same month.
Flat-rate charges one predictable rate no matter what card is used. It is easy to budget, and that is a real advantage for a small operation. The tradeoff is that a restaurant with a favorable card mix can pay more than it needs to, because a basic debit card and a premium rewards card cost you the same.
Tiered pricing sorts transactions into qualified, mid-qualified, and non-qualified buckets, and the processor decides which bucket each sale lands in. Rewards cards and keyed transactions often get pushed into the expensive tiers, and the pattern is hard to trace. Monument generally recommends moving away from tiered pricing when a better option exists, and restaurants have extra reason to: a single month mixes tipped checks, adjusted pre-auths, keyed catering orders, and online orders, which makes downgrades easy to miss.
On the traditional processing side, Monument builds custom interchange-plus, flat-rate, or tiered pricing rather than publishing one universal rate, because the right structure depends on your card mix, volume, and average ticket.
How Service Style Changes the Math
The same pricing model can feel fair in one room and expensive in another. Service style decides which transaction patterns dominate your month.
Full-service dining
Tip adjustments and split checks run the show. Nearly every table produces an adjustment after the first authorization, and split checks multiply the number of transactions per table while slowing the turn. Here, visibility matters most. You want to see what each adjusted ticket actually cost rather than trust a blended number, which usually points toward a transparent structure like interchange-plus.
Bars and nightclubs
Pre-authorized tabs and late closes drive the cost. Volume spikes late in the night, authorizations sit, and final captures rarely match the opening holds. Batch timing and tab handling move your effective rate more than the headline rate does, so a transparent pricing model and a POS with solid tab management matter most here.
Quick-service and cafes
Small tickets are the story. On a small ticket, any fixed per-transaction charge weighs proportionally more than it does on a large one, so a cost that disappears on a dinner check for four can be noticeable on a single coffee. Counter-service operators should look closely at how their pricing treats high-frequency, low-ticket sales, and at whether their guests are comfortable seeing a cash price and a card price.
Breweries and taprooms
A taproom runs bar-style tabs next to retail-style merchandise sales, plus the occasional release day or event that changes volume overnight. That mix rewards a setup flexible enough to handle both sides without penalizing either one.
Service style shapes seasonality too. A Western Slope cafe or taproom riding the summer tourist rush, or a ski-town kitchen in peak season, can see its volume and card mix shift sharply for a few months. A pricing structure that looked right in April can look wrong by February, which is one reason to review your numbers more than once a year.
How to Read a Processing Quote Before You Switch
Before you sign anything, sit down with two or three recent statements, ideally one slow month and one busy month, and hold every quote up against them:
- Separate interchange and assessments from processor markup. If the statement or the quote will not let you, that tells you something on its own.
- Find where tip adjustments and pre-auth settlements appear, and ask the provider how each one is priced.
- Ask how keyed catering orders and online orders are priced, and what triggers a downgrade.
- Compare your effective rate (total fees divided by total card volume), not the headline rate. The headline rate is what you were sold. The effective rate is what you paid.
- Ask whether the quote works with your current POS or assumes you will switch systems.
A full line-by-line statement walkthrough is a bigger subject for another day, but this short list is something you can do in one sitting, and it makes any quote much easier to judge.
Restaurant Merchant Services: Comparing Monument's Three Payment Programs
Restaurant merchant services are not one product. Monument offers three payment programs, and which one fits depends on your card mix, your guests, and your POS. Here is how the site states each one, side by side:
| Program | How it works at the register or table | Site-stated savings | Site-stated monthly fee |
|---|---|---|---|
| Traditional Processing | Conventional card acceptance with custom interchange-plus, flat-rate, or tiered pricing; no separate fee added for the guest | 10-15% savings | $25 flat monthly subscription with unlimited processing |
| Dual Pricing / Cash Discount | Card price shown before the guest pays (alone or next to a lower cash price); no fee added at checkout | Up to 100% savings | $25/month up to $5,000 monthly volume; $50/month for $5,000 to $10,000; $75/month for $10,000+ |
| Surcharging | Separately disclosed fee added only when a guest pays by credit card; debit handled differently | 40-60% savings | Not listed on the payment programs page |
A posted cash price tends to feel natural in counter-service spots and bars with a loyal regular crowd. Some full-service rooms, where the guest experience drives repeat visits, prefer to keep pricing simple and stay on traditional processing so nothing changes at the table. Surcharging sits somewhere in between and requires a venue that is comfortable showing a credit card fee as its own line on the check.
Fee recovery comes with real rules, so treat it as a setup project rather than a switch you flip. Surcharges apply only to credit cards, must show as a separate receipt line, are capped, and require advance notice through your processor. Visa's merchant surcharging guidance calls for notifying your acquirer 30 days before you start, and Monument handles that step for its merchants. Dual pricing needs a POS that can display both prices, plus the right signage. Rules vary by state, so Monument reviews them before recommending either program. For the full side-by-side, read Dual Pricing vs Surcharge: Which Fee Recovery Strategy Fits Your Business?, and see the dual pricing and surcharging program page for how implementation works.
If you run catering invoices or recurring commercial accounts, ACH deserves a look, because it charges a flat amount per transaction instead of a percentage. The payment programs FAQ puts ACH at typically $0.25 to $1.50 per transaction, compared with card processing at typically 2.5% to 3.5%. On a large catering invoice, that difference is hard to ignore, which is why some house accounts belong on ACH rather than a card on file.
Choosing a Restaurant Processor: POS and Contract Questions to Ask
Generic questions get generic answers. These are the ones that matter when you compare restaurant payment processing providers.
Can you keep your current processor? It depends on the system. Some POS platforms are processor-agnostic, and others require their own integrated processing. Know which kind you are looking at before you fall for a POS or a rate. Monument works with multiple processors and is not tied to a single provider, which keeps that decision open.
Does the setup support the workflows that drive your cost? Pre-auth tabs, tip adjustment, split checks, tableside payments, and online ordering integrations (DoorDash and Uber Eats, depending on the system) are not feature-list filler. They are the mechanics that decide what each transaction costs and how fast your staff can close a check. The restaurant pages on Monument's site name Union POS, Clover, TableTurn POS, and Square among the systems it deploys for restaurants. The useful question is which workflows each one handles well for your service style, not which logo is on the screen.
Is the pricing transparent enough to check every month? If you cannot separate markup from interchange on the statement, you cannot verify a single promise in the quote.
Does anyone watch your rates after go-live? Good quotes have a way of drifting. Ongoing monitoring and regular reviews are what keep a fair arrangement fair.
Are there long-term contracts? The payment programs page states no long-term contracts and no sales pressure. Whoever you talk to, ask the question and get the answer in writing.
How Monument Evaluates a Restaurant's Processing Setup
The process Monument describes is straightforward: listen, evaluate, recommend, deploy, and support.
Listen and evaluate. It starts with how your service actually runs, from kitchen routing to where cards change hands, along with a review of your current statement. Card mix, guest base, and POS get looked at together, because a program that ignores any one of them will fit poorly.
Recommend. The payment program is matched to the venue, and compliance is reviewed before any fee recovery program is put on the table, not after.
Deploy. Processor setup, POS configuration, signage and receipt formatting where fee recovery applies, and training for both front and back of house before go-live.
Support. Ongoing rate monitoring and annual processing reviews after launch.
For restaurants across Colorado, that work happens on-site, out of Grand Junction. Everyone else gets the same evaluation and configuration remotely, in any of the 50 states. Monument lists ETA Certified Payment Professional credentials on its site, along with 500+ merchants served and PCI DSS compliance. The point of the sequence is simple: the recommendation should come from watching how your room works on a Friday night, not from a rate sheet.
Get a Free Evaluation of Your Restaurant's Processing
Restaurant fees hide in tips, pre-auths, keyed orders, and the mix of card-present and online traffic, and the real savings lever is the right pricing structure with a fair markup, not one negotiated number. To see what that looks like on your own statements, start a free evaluation on the Monument payment programs page or call (970) 239-1307.
Recent Posts